The most oversold product in lending, explained without the pitchman: what it does, what it costs you, and who it's actually wrong for.
If you've seen the commercials, you already have the fear: that a reverse mortgage is a trick, that someone is going to take the house, that the bank ends up owning the home you spent thirty years paying off. That fear is reasonable, and it's common, because this is the most oversold product in lending. The honest version is quieter than the TV version, and quieter is what you want.
So here is the quiet version. You keep the title. The home is yours, same as yesterday.
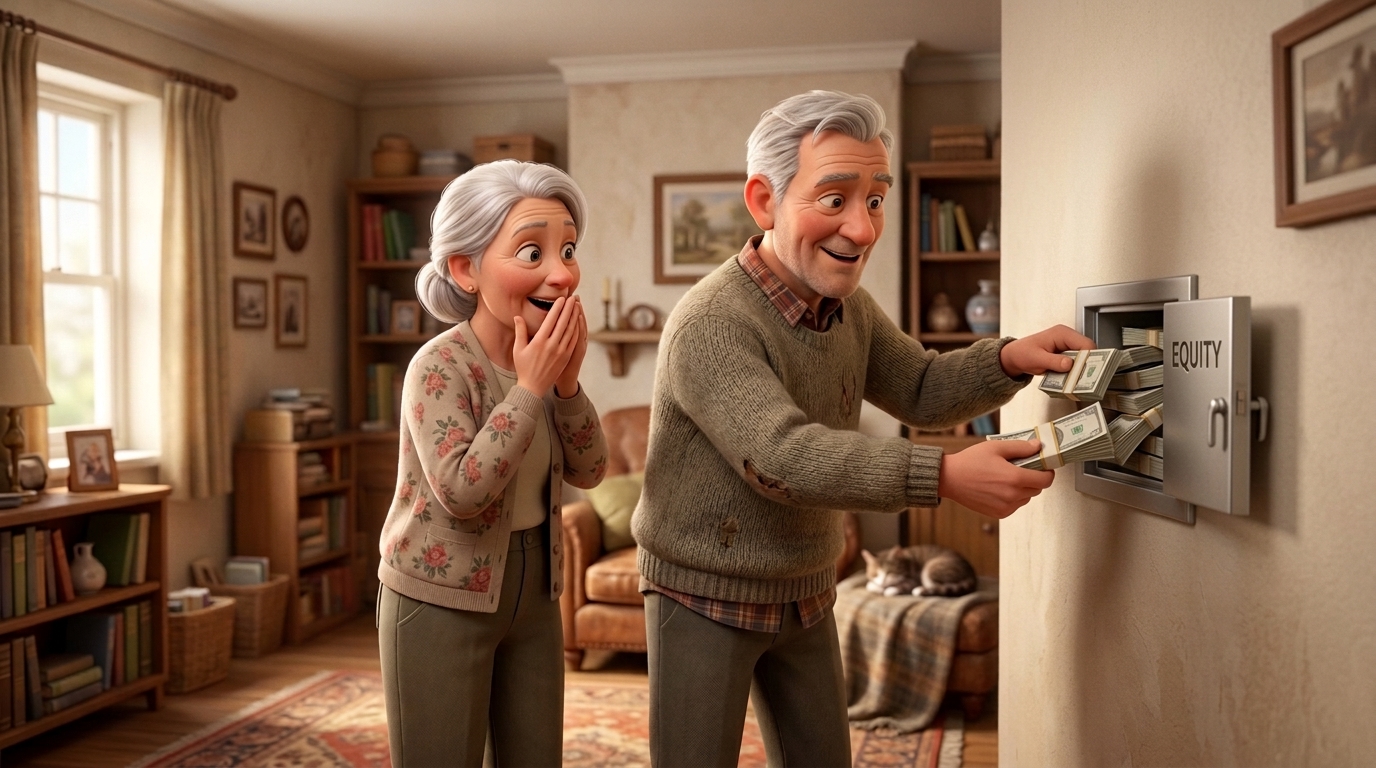
If you're 62 or older and you live in the home as your primary residence, a reverse mortgage lets you turn some of your equity into money without a monthly mortgage payment. That last part is the whole appeal: cash out of the walls, nothing due each month.
The catch is the part the commercials rush past. The loan still grows. Interest and fees pile onto the balance instead of coming out of your pocket monthly, so the amount owed goes up over time, not down. You are spending equity today that your heirs would otherwise inherit. That isn't a scandal, it's just the mechanism, and you should decide with it in full view.
Two things stay firmly yours, and they matter. You keep the title, and you keep the bills. Property taxes, homeowners insurance, and upkeep remain your responsibility, and falling behind on those is one of the few ways this goes wrong. It's less like selling the house and more like running the heat off a battery instead of the grid: convenient, real, and it draws down a thing you can see the bottom of.
The loan comes due when the last borrower sells, moves out for good, or passes away. The home is sold, the balance is paid, and whatever equity is left goes to your heirs. If the balance ever runs past the home's value, that's the lender's problem, not your kids'.
If you're thinking of using it to cover a short gap and you plan to move in a couple of years, the upfront costs usually eat the benefit. If leaving the house to your children is the priority above all else, this spends the thing you want to leave. In those cases, staying put without this loan is the right answer, and that's a path, not a door closing. There are other tools, including a plain refinance or a HELOC, and sometimes the answer is none of them.
Before you can proceed, federal rules require independent counseling with an approved third party. People hear "required" and brace. Don't. It's the one hour in this whole process whose only job is you understanding what you're signing, and it's a good thing.
Your number needs your numbers. But the first move isn't signing anything. It's looking, with someone who'll tell you when the answer is no.
Educational content only — not a loan offer, rate quote, or commitment to lend. Program guidelines are general; your actual options depend on your full financial picture. Nic Feinstein, NMLS# 2830139, RanLife Home Loans (Corporate NMLS# 3151). Equal Housing Lender.