When your rate, PMI, opportunities, or debt has real room to move, refinancing pays off. When it doesn't, the honest answer is to wait.
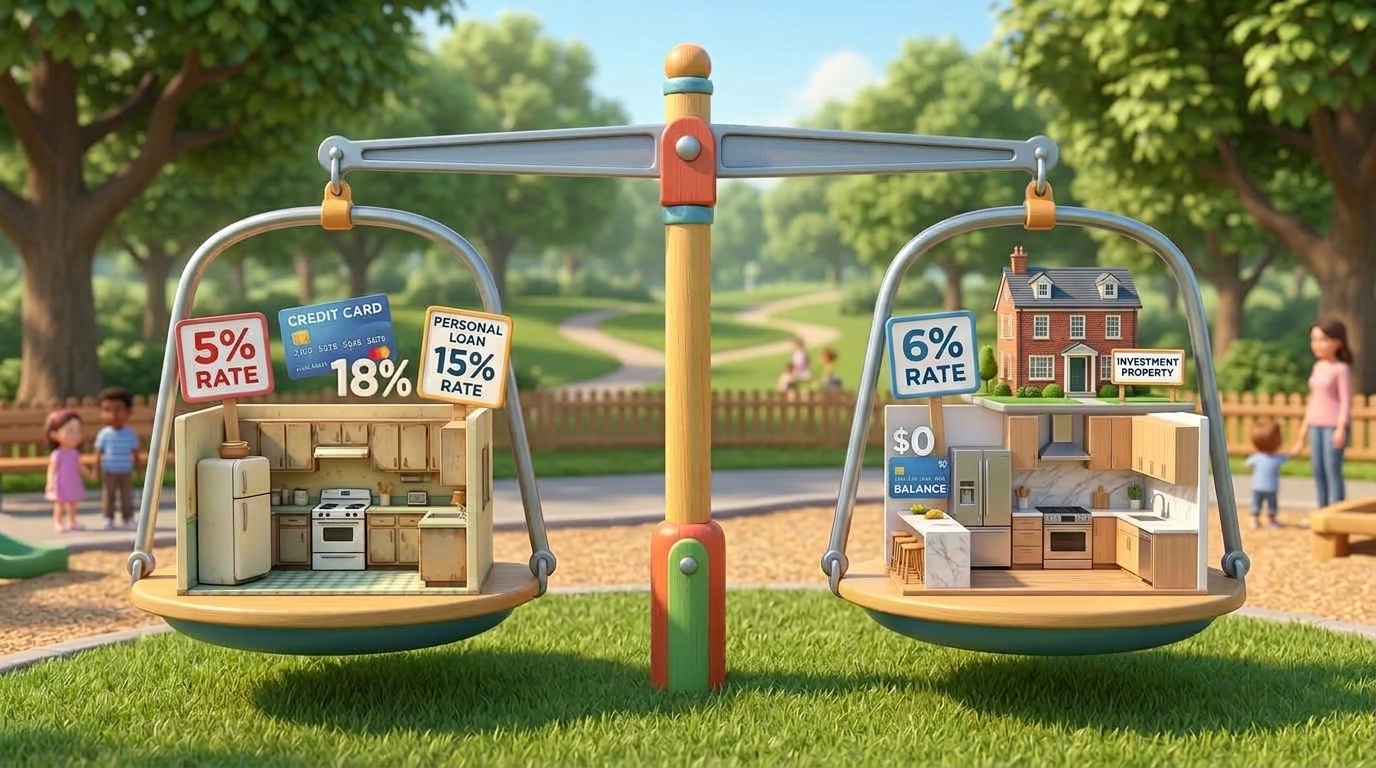
Most people put off asking about a refinance because they're afraid the answer is a sales pitch dressed up as advice. You've heard the ads. Somebody's always telling you now is the moment, and you can't tell whether the moment is real or whether it's just their moment to close a deal. That instinct is correct, and it's common. A refinance is either math that works or math that doesn't, and if it doesn't, the right move is to leave your loan alone. So let's do the math out loud.
A refinance replaces your current mortgage with a new one, and it costs money to do. Closing costs are real, whether they come out of pocket or get rolled into the loan. So the question is never "is my rate higher than today's rate." The question is whether the savings outrun those costs before you sell or move.
Here is the honest version of when it's worth a look:
Equity is the part most Arizona owners underestimate. Recent appreciation here has done quiet work on a lot of loans, and the PMI you started with may already be gone on paper even if it's still on your statement.
Think of it like a repair on a car you're about to keep. If the fix costs $2,000 and saves you $100 a month, you break even in twenty months. Keep the car three years and it was smart. Sell it in a year and you lost money. A refinance is the same calculation, exactly.
So we take your closing costs, divide by your real monthly savings, and get the month you start winning. If you'll still own the home well past that month, the refinance works. If you're not sure you'll be here that long, it may not, and I'll tell you so.
I can't give you your number from an article, because your number needs your numbers: your balance, your equity, your dates. General guidance is all a page can honestly offer.
Applying is how you find out, not what you commit to. A submitted application obligates you to nothing. If the math says wait, that's a path, not a door closing: I'll watch the rate and tell you when your moment is actually here. And if the math already works, you'll know that too, and we move.
Educational content only — not a loan offer, rate quote, or commitment to lend. Program guidelines are general; your actual options depend on your full financial picture. Nic Feinstein, NMLS# 2830139, RanLife Home Loans (Corporate NMLS# 3151). Equal Housing Lender.