A lower rate for 5–10 years, then it moves. Whether that's smart or expensive comes down to one honest answer.
The fear with an adjustable-rate mortgage is that you'll take the lower payment now and get ambushed later, when the rate jumps and you're stuck in a house you can't afford to leave. That fear is correct, for some people. The whole job of this article is telling you whether you're one of them, and most people have never had anyone lay out the actual mechanics instead of just warning them off.
So let's lay them out.
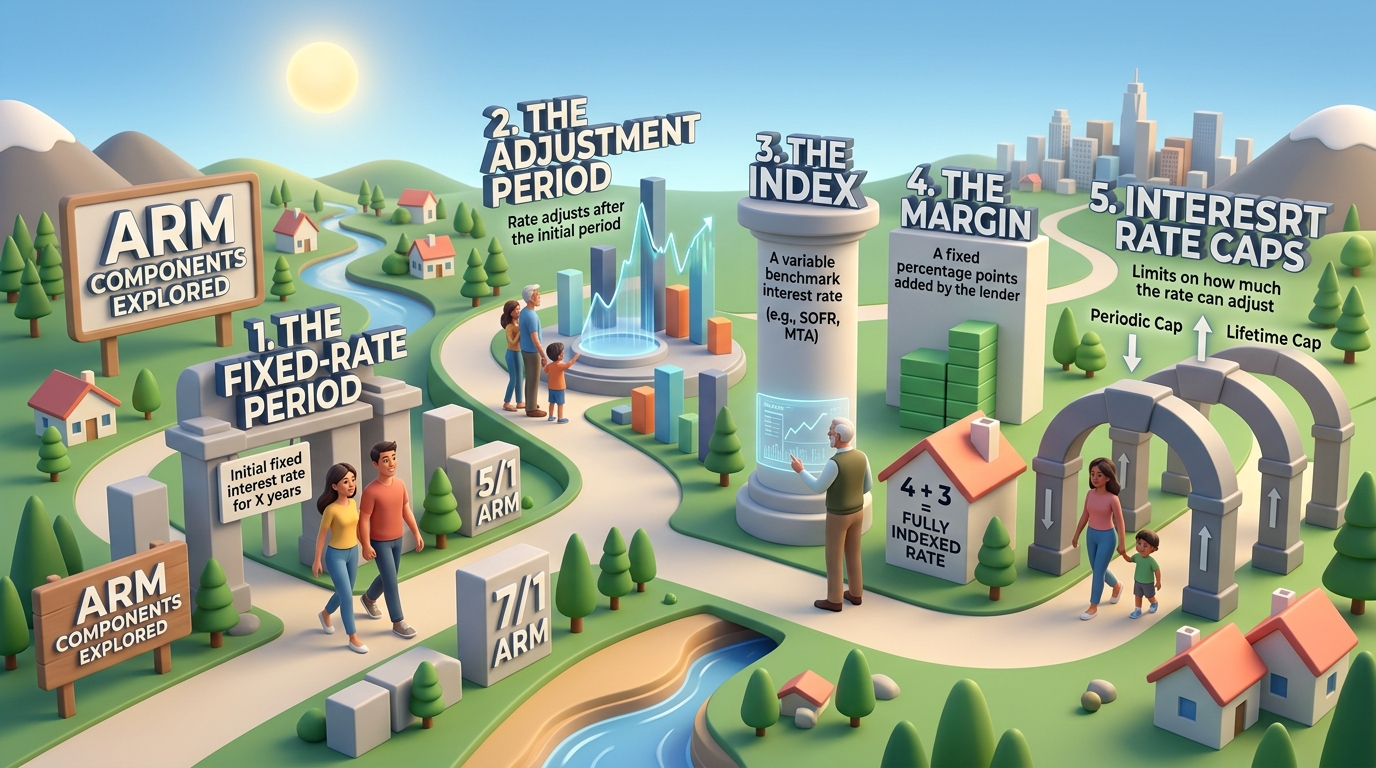
An ARM, Adjustable Rate Mortgage, gives you a fixed rate for a set stretch, usually 5, 7, or 10 years, and then it adjusts with the market for the rest of the loan. That's it. Everything else is detail.
Which means the question isn't really "is an ARM good or bad." It's: will you be out of this loan before the fixed period ends? Not "might you." Will you. People genuinely expecting to move, refinance, or pay the thing off inside that window are the people an ARM is built for. They get the lower rate and leave before the gamble starts.
The honest part is hard, because "I'll probably move in five years" is a hope, not a plan. Plenty of people say it and are still there in year nine.
Every ARM has three caps, and they are the real contract. How much the rate can move at the first adjustment, how much it can move each year after, and how high it can go over the life of the loan. That lifetime cap is your worst case, and you should know it as a number before you sign anything, not as a surprise.
Two things that get missed: today's ARMs are not the 2008 kind. You qualify at a stressed rate, not the teaser, so the loan was never approved on a payment you can only make at the low rate. And when ARM and fixed rates are close together, the ARM isn't worth the risk. You're taking on uncertainty to save almost nothing. In that case, just take the fixed.
Life keeps people in houses. A job stays, a baby arrives, the market shifts and refinancing isn't there when you wanted it. So the honest version of this loan includes a plan B: what happens if you're still here at first adjustment, and can you carry the payment near that lifetime cap. If the answer is no, that's a real no, and it's the one that protects you.
The gamble only pays if the timeline is real. Your call on that is the whole thing, and nobody else can make it for you.
Educational content only — not a loan offer, rate quote, or commitment to lend. Program guidelines are general; your actual options depend on your full financial picture. Nic Feinstein, NMLS# 2830139, RanLife Home Loans (Corporate NMLS# 3151). Equal Housing Lender.